
Square Accounting · CPA-led tax advisory
Real estate tax planning for Florida investors.
Before you buy, change ownership or sell, understand how the decision could affect your taxes and available cash. Square Accounting helps Florida rental property investors evaluate ownership, depreciation, rental losses and sale options before acting.
Tell us what you’re considering and when you need to decide.
See what a planning review considersPlan around your property
- Ownership
- Rental income
- Future sale
Each decision shapes what comes next.
Before a purchase
Review ownership, financing and intended use while those choices are still open.
While you own
Revisit the plan when income, participation, property use or improvement plans change.
Before a sale
Discuss the tax and cash consequences, including whether an exchange is worth evaluating.
Four planning areas, one connected review
What your real estate tax review covers.
The right question goes beyond “Can I deduct this?” It includes when the deduction helps, what the choice costs and how it fits your plans for the property.
Property ownership and tax structure.
Who owns the property, how it is used and how that ownership is taxed all belong in the review. Changes should also be considered with your attorney when legal documents or liability questions are involved.
- The decision
- How should the ownership and tax treatment fit your partners, financing and future plans?
- Useful records
- Current ownership details, entity documents, loan terms and proposed purchase or transfer documents.
Depreciation and cost segregation.
Before commissioning a study, consider its cost, the timing of deductions, your ability to use them and your expected holding period.
- Land
- The cost of land is not depreciable.
- Rental property
- Depreciation begins when the property is ready and available for rent.
- Useful records
- Closing statement, improvement invoices, rental availability date and existing depreciation schedule.
Rental losses and participation.
Rental real estate losses generally face passive activity limits. Exceptions depend on the activity, your participation and other requirements. A projected loss does not automatically offset salary.
- The decision
- Would a deduction reduce tax now, or could the resulting loss be limited or carried forward?
- Useful records
- Prior returns, unused-loss schedules and records of the work you and others perform for the property.
Property sales and 1031 exchanges.
A qualifying 1031 exchange can defer gain on eligible business or investment real estate. Eligibility, transaction structure and timing matter. Discuss the options before committing to the sale.
- Tax on gain
- Debt and selling costs
- Cash to reinvest
- The decision
- How do a taxable sale and a potential exchange compare with keeping the property and with your need for cash?
- Useful records
- Purchase and improvement costs, depreciation history, loan balance and expected sale terms.
The review depends on your facts and the agreed engagement. Confirm whether tax preparation, specialist studies and ongoing support are included when discussing the scope.
The people and the process
Your tax advisor and planning process.
You should understand who you’re speaking with, what information matters and how the work would begin.
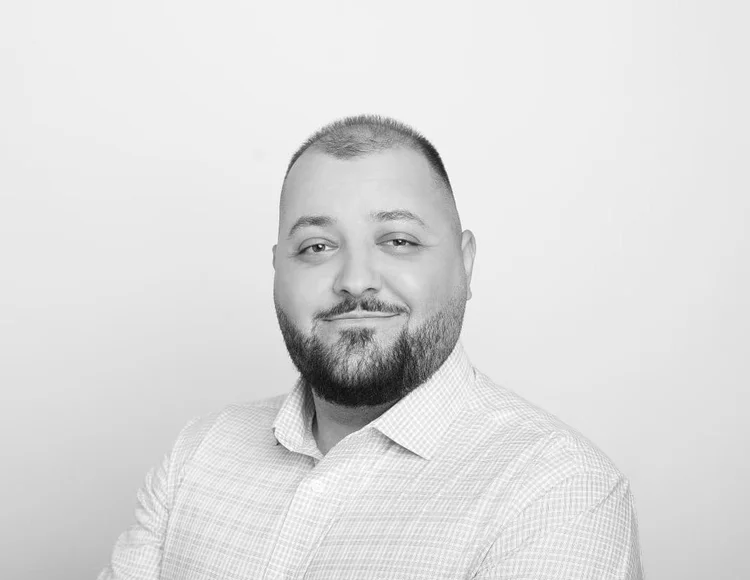
The person behind the advice
Stevan Franeta, CPA
Senior Tax Advisor
Square Accounting
Stevan Franeta, CPA, is Square Accounting’s Senior Tax Advisor. His work focuses on long-term tax strategies for business owners and investors. The conversation starts with what you want the property to do for you.
That might mean keeping cash available for another purchase, understanding a rental loss or weighing a sale. The property decision and your wider tax picture belong in the same conversation.
Meet Stevan and the Square Accounting teamHow the work begins
How a planning engagement starts.
Discuss the fit
Talk through your situation and whether a planning engagement addresses the question you need to answer.
Agree on the work
Clarify the scope, fees, records needed and who handles any preparation or specialist work.
Evaluate the choices
Within the agreed scope, review the relevant facts, trade-offs and next steps before implementing the plan.
Already work with a CPA? Tell us what they handle so any division of responsibilities can be agreed from the start.
Before you reach out
Real estate tax planning questions.
A few details can help you decide what kind of support you need.
How is tax planning different from tax preparation?
Tax planning evaluates choices and their likely consequences while decisions remain open. Tax preparation reports transactions under the applicable rules. Confirm how preparation, implementation and ongoing advice would be included in your engagement.
Can rental losses reduce tax on my salary?
It depends on how the activity and your participation are classified and which loss limits apply. Rental real estate is generally passive, with exceptions. We need your facts before treating a projected loss as a current-year tax benefit.
Does real estate professional status make rental losses deductible?
Not by itself. Under the real estate professional exception, you must qualify for that status and materially participate in the rental activity for it to be nonpassive. Other loss limits may still apply. A review should consider the qualification tests, participation records and limits that affect your return. IRS rules for real estate professionals and rental losses
Should I arrange a cost segregation study first?
Start by asking whether the resulting deductions would be useful in your circumstances. The property, income, loss limits, study cost and expected holding period all belong in that decision. Confirm who would prepare any study and how that work is priced.
What if I already have a CPA?
Tell us what your current accountant handles and which question remains unresolved. That helps identify where a separate planning engagement could add value. Any division of work or coordination should be agreed before the engagement begins.
What should I prepare for the first conversation?
Start with a short description of the properties you own, the decision you are considering and any approaching dates. If you move forward, we will confirm the records needed and how to provide them through the appropriate client system. Read the tax strategy review preparation checklist
For the rental-loss and REPS rules: IRS Publication 925.
Let’s discuss your next property decision
Discuss your next property decision.
Buying, reviewing an existing portfolio or preparing to sell? Tell us what is changing and what you need to understand before you act.