
A useful year-end tax planning checklist for business owners should tell you which decisions still need action before 2026 closes, which can legally wait, and which should be rejected even if they produce a current deduction. For a high-income Florida owner, the sequence matters: project the 2026 return and a directional 2027 case, separate estimated-tax protection from the actual tax bill, finish decisions with genuine year-end deadlines, then test discretionary deductions against liquidity and future tax consequences.
Not every item expires December 31. The fourth regular 2026 federal estimated-tax installment is generally due January 15, 2027. Employer retirement contributions and SEP funding can have later deadlines. By contrast, a 401(k) elective deferral generally cannot be created after the compensation is already available, and depreciable property generally must be placed in service during the tax year to affect that year's depreciation.
The article’s planning sequence moves from projection and payment analysis to deadline-sensitive actions and multi-year evaluation.
“A useful year-end tax planning checklist for business owners should tell you which decisions still need action before 2026 closes, which can legally wait, and which should be rejected even if they produce a current deduction.”
Key Takeaways
Projection comes before tactics. A deduction is not automatically valuable just because it is available in 2026.
Safe harbor and full funding are different targets. You can manage underpayment-penalty exposure and still owe a large balance at filing.
Year-end deadlines are transaction-specific. Payroll elections, employer retirement contributions, SEP funding, investment sales, charitable gifts, and placed-in-service dates do not share one universal cutoff.
For service-business owners, owner-level interactions matter. Compensation, QBI, investment gains, charitable deductions, and retirement funding can converge on the same individual return.
The best current-year move can be the wrong multi-year move. Liquidity, future deductions, depreciation recapture, and a possible sale or ownership change can reverse the apparent benefit.
How to Use This Year-End Tax Planning Checklist for Business Owners
Start with the decisions that are hardest to reverse. The table below separates the legal timing question from the planning question.
| Decision | Last practical decision point | What to model or document |
|---|---|---|
| Decision 2026 and 2027 tax projection | Start before other discretionary moves | Business income, wages, K-1 items, gains, deductions, credits, withholding |
| Decision Estimated tax and withholding | Recalculate before final payroll and January payment | Safe-harbor target, projected total tax, prior payments, cash reserve |
| Decision S corporation compensation | Before final 2026 payroll is closed | Duties, time, comparable pay, distributions, benefits, withholding |
| Decision 401(k) elective deferrals | Before compensation becomes currently available, subject to plan terms | Election, payroll timing, plan limits |
| Decision Employer 401(k) contributions | Often after year-end if statutory conditions are met | Plan terms, compensation, return due date |
| Decision SEP establishment and funding | Potentially through the business return due date, including extensions | Eligibility, contribution calculation, funding deadline |
| Decision Equipment and other depreciable property | Property must satisfy the applicable placed-in-service rules for 2026 treatment | Business need, qualification, cash impact, future sale or recapture |
| Decision Charitable gifts | Complete the contribution under the applicable delivery rule | 2026 AGI, 0.5% floor, substantiation, noncash valuation |
| Decision Investment gains and losses | Complete the sale in 2026 | Realized gains, NIIT, wash-sale window, replacement purchases |
| Decision Cash-method income and expenses | Before rights to income or deductions are fixed | Constructive receipt, payment date, prepaid-expense rules |
The table is a triage tool, not a conclusion. A move still has to make economic sense after the tax effect is measured.
Compare your 2026 deadlines, projected tax position, and 2027 assumptions in one coordinated review.
1. Build the 2026 Projection, Then Run a 2027 Case
For a high-income owner, year-end planning should begin with the individual return that ultimately absorbs the business and investment activity. That often means combining W-2 wages, Schedule C income, partnership or S corporation K-1 items, spouse income, realized gains, retirement contributions, itemized deductions, credits, federal withholding, and estimated payments.
Then add a directional 2027 forecast. It does not need false precision. It needs enough information to answer whether next year is likely to be materially higher or lower and whether a major transaction is approaching.
Useful inputs include:
expected changes in business profit;
a planned sale, acquisition, financing event, or ownership change;
a large 2027 capital expenditure;
expected investment gains;
a compensation or retirement-plan change; and
any event likely to change taxable income or liquidity materially.
That second-year view changes the meaning of “accelerate the deduction.” If 2026 is unusually high and 2027 is expected to be lower, a supportable 2026 deduction may be more valuable. If 2027 income is likely to be materially higher, preserving deductions or cash for next year may be preferable.
Include QBI when the owner is near a Section 199A threshold
Public Law 119-21 extended Section 199A without the former post-2025 sunset and changed the phase-in range. For 2026, the threshold is $403,500 for married taxpayers filing jointly and $201,750 for most other returns, with a $150,000 joint phase-in range and a $75,000 phase-in range for most other filers.
For a service-business owner, the classification of the business can matter. Specified service trades or businesses are subject to additional limitations once taxable income enters and exceeds the applicable phase-in range. The practical point is that compensation, retirement contributions, deductions, and other items that change taxable income can also change the Section 199A result. Do not model QBI as a guaranteed flat 20% deduction.
Examine how a 2026 decision may affect cash flow, deductions, and the directional 2027 tax picture.
2. Separate Estimated-Tax Protection From the Actual Tax Bill
For most individuals, the federal required annual payment used to manage estimated-tax underpayment exposure is generally the smaller of 90% of expected 2026 tax or 100% of the tax shown on the 2025 return. For many higher-income taxpayers, the prior-year percentage is 110% when 2025 AGI exceeded $150,000, or $75,000 for married filing separately. Farmers, fishers, and certain other taxpayers can have different rules.
That calculation is not the projected 2026 liability.
Keep three numbers separate:
Projected 2026 total tax: what the current facts suggest the year will ultimately cost.
Required annual payment: the amount generally needed through timely estimates and withholding to manage federal underpayment-penalty exposure.
Tax cash reserve: the liquidity you intend to retain for the projected balance and remaining payments.
The year-end payment decision is clearer when projected liability, required prepayments, and cash reserves are treated as separate planning inputs.
“Keep three numbers separate”
A growing owner can satisfy the prior-year safe harbor and still have a substantial filing-season balance. That is a cash-planning issue even when the safe-harbor calculation is working as intended.
For a deeper treatment of the payment mechanics, Square Accounting's 2026 quarterly estimated-tax guide for Florida business owners separates projected liability, required prepayments, and cash reserves.
The fourth regular 2026 payment is generally due January 15, 2027
For a calendar-year individual, the regular fourth estimated-tax installment is due January 15, 2027. If the 2026 return is filed by January 31, 2027 and the remaining tax is paid by that date, Publication 505 provides an exception to the January 15 payment in qualifying circumstances.
If income arrived unevenly during the year, the annualized-income installment method may reduce the required installment for one or more periods. A taxpayer using that method must file Form 2210 with the 2026 return and use Schedule AI as applicable.
Review withholding before final payroll
Withholding is generally treated as paid evenly through the year for the standard underpayment calculation unless the taxpayer elects to establish the actual withholding dates. That can make additional legitimate late-year withholding materially different from simply making a late estimated payment. The right approach depends on the existing shortfall, available payroll, and the Form 2210 calculation.
3. Finish the S Corporation Compensation Review Before Payroll Closes
An S corporation must pay reasonable compensation to a shareholder-employee for services before treating amounts as non-wage distributions in place of compensation. The IRS does not prescribe a universal salary-to-profit percentage. It looks to facts such as training, duties, time and effort, compensation practices, comparable pay, and the source of the corporation's gross receipts.
For a professional or consulting business, that last point can be especially important. The IRS distinguishes receipts generated by the shareholder's personal services from receipts attributable to nonshareholder employees, capital, and equipment. That does not produce a mechanical formula, but it gives the compensation analysis a factual structure.
Before the final payroll, review:
year-to-date W-2 compensation;
the owner's actual role and time commitment;
distributions already taken;
bonus decisions;
federal withholding;
retirement contributions tied to compensation;
shareholder health-insurance treatment where applicable; and
whether payroll and the books tell the same story.
If the issue is broader than the final paycheck, the existing Florida business entity structure review addresses ownership, tax classification, financing, and exit considerations that a payroll adjustment alone cannot solve.
4. Treat Retirement Deadlines as Separate Clocks
For 2026, the basic elective-deferral limit for most 401(k) plans is $24,500. The general catch-up limit for participants age 50 or older is $8,000. For participants who turn 60, 61, 62, or 63 during 2026, the higher catch-up limit is $11,250 when the plan permits it.
Beginning in 2026, participants in plans with Roth features that offer catch-up contributions generally must make catch-up contributions on a Roth basis if their prior-year wages from the plan sponsor exceeded $150,000.
Those limits answer “how much.” They do not answer “by when.”
Employee elective deferrals
A 401(k) cash-or-deferred election generally can apply only to compensation that is not already currently available to the employee. Retroactive elective deferrals are generally not permitted. Existing plan terms and payroll processing therefore matter before the final compensation is paid or made available.
Employer contributions
An employer can generally deduct qualifying profit-sharing or matching contributions made after year-end if the statutory conditions are met and the contribution is paid by the employer's return due date, including extensions.
First-year one-participant 401(k) exception
A narrow exception applies to an individual who owns the entire interest in an unincorporated business and is its only employee. For the first year of a new 401(k), that owner may adopt the plan after year-end and elect to defer prior-year self-employment earnings as late as the due date of the individual's return, determined without extensions. The rule should not be generalized to an S corporation shareholder-employee or a business with employees.
SEP timing
A SEP can generally be established as late as the due date, including extensions, of the business income-tax return for the year. Contribution timing and the deductible amount still depend on the business's facts and contribution calculation.
The planning task is therefore to identify the plan, contribution type, compensation base, payroll cutoff, and actual statutory deadline before moving cash.
5. Use Depreciation to Support a Business Decision, Not Create One
Current law provides a permanent 100% additional first-year depreciation deduction for qualified property acquired and placed in service after January 19, 2025, subject to the qualification rules and elections under Section 168(k).
For tax years beginning in 2026, the Section 179 maximum is $2,560,000. The limit is reduced when the cost of Section 179 property placed in service during the year exceeds $4,090,000. Section 179 also has a taxable-business-income limitation and other eligibility rules.
Those rules can make a 2026 purchase tax-efficient. They do not answer whether the purchase should happen.
Before accelerating a planned asset purchase, test four facts:
Would the business buy the asset without the tax deduction?
Can the asset actually be ready and available for its intended business use in 2026?
What happens to working capital, financing capacity, and 2027 operating needs?
What happens if the asset is sold or its business use falls later?
The last question is easy to miss. Section 179 can be recaptured if business use later drops to 50% or less during the recovery period. On a sale of depreciable Section 1245 property, gain can be treated as ordinary income to the extent of depreciation allowed or allowable, subject to the detailed recapture rules.
Alternate-facts example
Assume a Florida consulting company plans to buy $80,000 of qualifying technology equipment in early 2027. The equipment can legitimately be delivered, installed, and ready for business use in December 2026.
Case A: 2026 is an unusually high-income year, 2027 income is expected to fall, the company has ample working capital, and there is no near-term plan to sell the equipment or business. Accelerating the purchase may improve the timing of deductions.
Case B: 2027 income is expected to rise, the company needs cash for hiring in January, and a business sale is being considered within two years. The same accelerated deduction can be less attractive because it uses liquidity now and can reduce basis or affect gain characterization when depreciable assets are later sold.
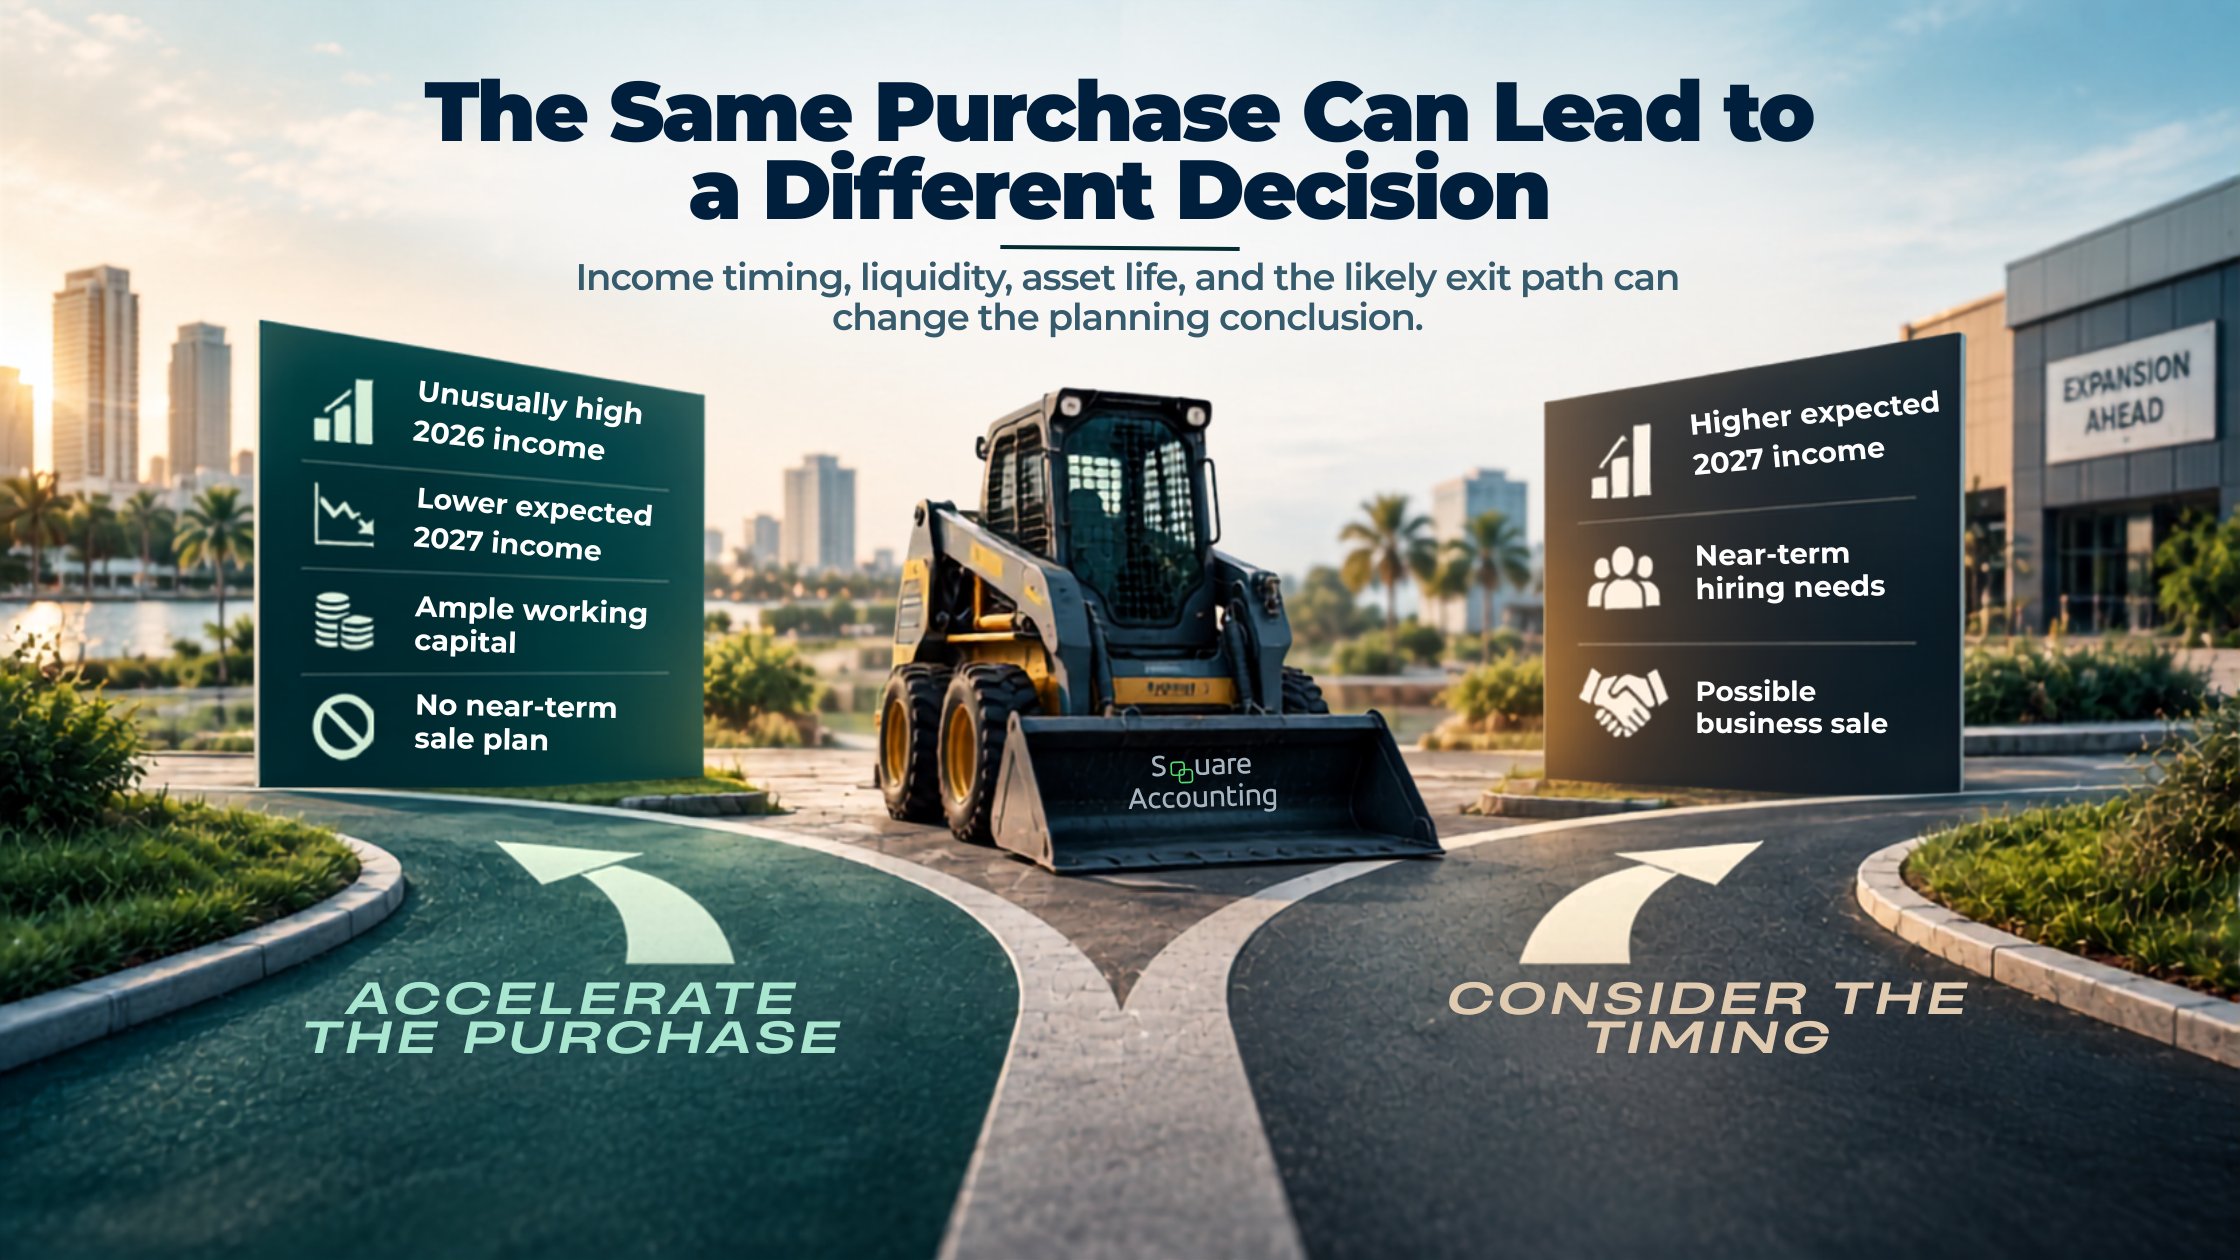
The article’s equipment scenario shows why the tax rule alone does not determine whether accelerating a purchase makes sense.
“The same accelerated deduction can be less attractive because it uses liquidity now and can reduce basis or affect gain characterization when depreciable assets are later sold.”
The tax rule is only one input. The better decision depends on income timing, liquidity, asset life, and the likely exit path.
Review whether an accelerated 2026 asset purchase fits the projected tax position, liquidity needs, and likely disposition path.
6. Manage Cash-Method Timing Without Manufacturing It
Cash-method taxpayers generally include income when actually or constructively received. Income is constructively received when it is credited to the taxpayer's account or otherwise made available without substantial restriction. Simply delaying a deposit does not necessarily move income to the following year.
Expense timing has a similar limit. A cash-method business generally deducts expenses when paid, but advance payments can be subject to capitalization rules. Under the 12-month rule, certain prepaid rights or benefits may avoid capitalization only when they do not extend beyond the earlier of 12 months after the benefit begins or the end of the following tax year.
Before changing billing or payment timing, document:
when the customer became obligated to pay;
when funds were actually or constructively available;
when the business paid the expense;
what period a prepaid item covers; and
whether a related-party or other special timing rule applies.
The goal is to use the accounting method correctly, not to create a year-end date that the underlying facts do not support.
7. Recalculate Charitable Giving and SALT Under the 2026 Rules
Beginning in 2026, an individual who itemizes generally deducts charitable contributions only to the extent they exceed 0.5% of AGI, subject to the other charitable-contribution limitations.
For an owner who gives materially each year, this makes the timing of gifts more relevant. Compare expected 2026 and 2027 AGI, whether itemizing is likely in each year, and whether bunching gifts into one year changes the usable deduction.
Implementation matters. IRS guidance generally treats a charitable contribution as made when it is unconditionally delivered. Different delivery rules apply to checks, credit cards, and property transfers. Recordkeeping also changes with the type and amount of the gift, and noncash gifts can require acknowledgments, Form 8283, or a qualified appraisal depending on the facts.
The federal SALT limit also changed. For 2026, the limit on deductible state and local income, sales, and property taxes is $40,400, or $20,200 for married filing separately. The limit begins to reduce when MAGI exceeds $505,000, or $252,500 for married filing separately, and cannot be reduced below $10,000, or $5,000 for married filing separately.
Florida's lack of individual income tax changes the mix of taxes in that calculation, but not the federal mechanics.
8. Coordinate Business Income With Investment Gains and Losses
The 3.8% Net Investment Income Tax applies to the lesser of net investment income or the excess of modified adjusted gross income over the statutory threshold. For individuals, the thresholds include $250,000 for married filing jointly, $125,000 for married filing separately, and $200,000 for single or head-of-household filers. The thresholds are not indexed for inflation.
Net investment income generally includes items such as interest, dividends, capital gains, rental income, and royalties. Most self-employment income is generally excluded, but the classification of pass-through, rental, and disposition income can depend on the underlying facts.
That is why an owner-level projection matters. A large business-income year can push MAGI above the threshold while a separate portfolio transaction creates the net investment income subject to the tax.
Tax-loss harvesting can offset realized capital gains, but the wash-sale rule can disallow a loss when substantially identical stock or securities are acquired within 30 days before or after the sale. The IRS also applies the rule to certain acquisitions in an IRA or Roth IRA, and a spouse's or controlled corporation's purchase can matter.
Before harvesting a loss, review planned repurchases and automated transactions across relevant accounts rather than looking only at the account in which the sale occurs.
9. Florida Changes the State Layer, Not the Federal Decision
Florida does not impose a personal income tax. A Florida resident therefore does not file a Florida personal income-tax return simply because business or investment income is high.
That does not make every Florida business tax-free at the state level. The Florida Department of Revenue administers corporate income tax for corporations and other entities within that regime, and the rate is 5.5% for taxable years beginning on or after January 1, 2022.
Depending on the business's facts, Florida reemployment tax can apply to employers, and sales or use tax can apply to taxable transactions. Florida DOR also imposes registration and filing requirements on businesses within those systems.
The practical Florida year-end review is therefore narrower than a generic “state-tax” section:
confirm whether the owner has only federal individual income-tax exposure or an entity-level Florida income-tax filing;
review payroll and reemployment-tax obligations if the business has employees;
determine whether the business makes taxable Florida sales or has use-tax exposure; and
identify activity outside Florida that should be reviewed under the other state's rules before assuming Florida residency resolves the issue.
For a broader exposure framework, see Square Accounting's Florida Tax Exposure Scorecard.
10. Use a Four-Step Filter Before Approving a Year-End Move
A proposed strategy should pass four separate tests.
1. Legal timing
What event controls the tax year: election, payment, delivery, payroll, sale date, or placed-in-service date? A December 31 deadline should never be assumed merely because the strategy is discussed at year-end.
2. Current-year tax effect
Is the result a deduction, credit, exclusion, deferral, payment-timing change, or basis adjustment? Label the effect correctly before calling it “savings.”
3. Multi-year cost
What changes in 2027 and later? Consider cash reserves, lost future deductions, depreciation recapture, retirement capacity, basis, and any expected sale or ownership transition.
4. Implementation and evidence
Who has to act, what document or election must exist, what payroll or accounting entry must be completed, and what records should be retained? A projection is not implementation.
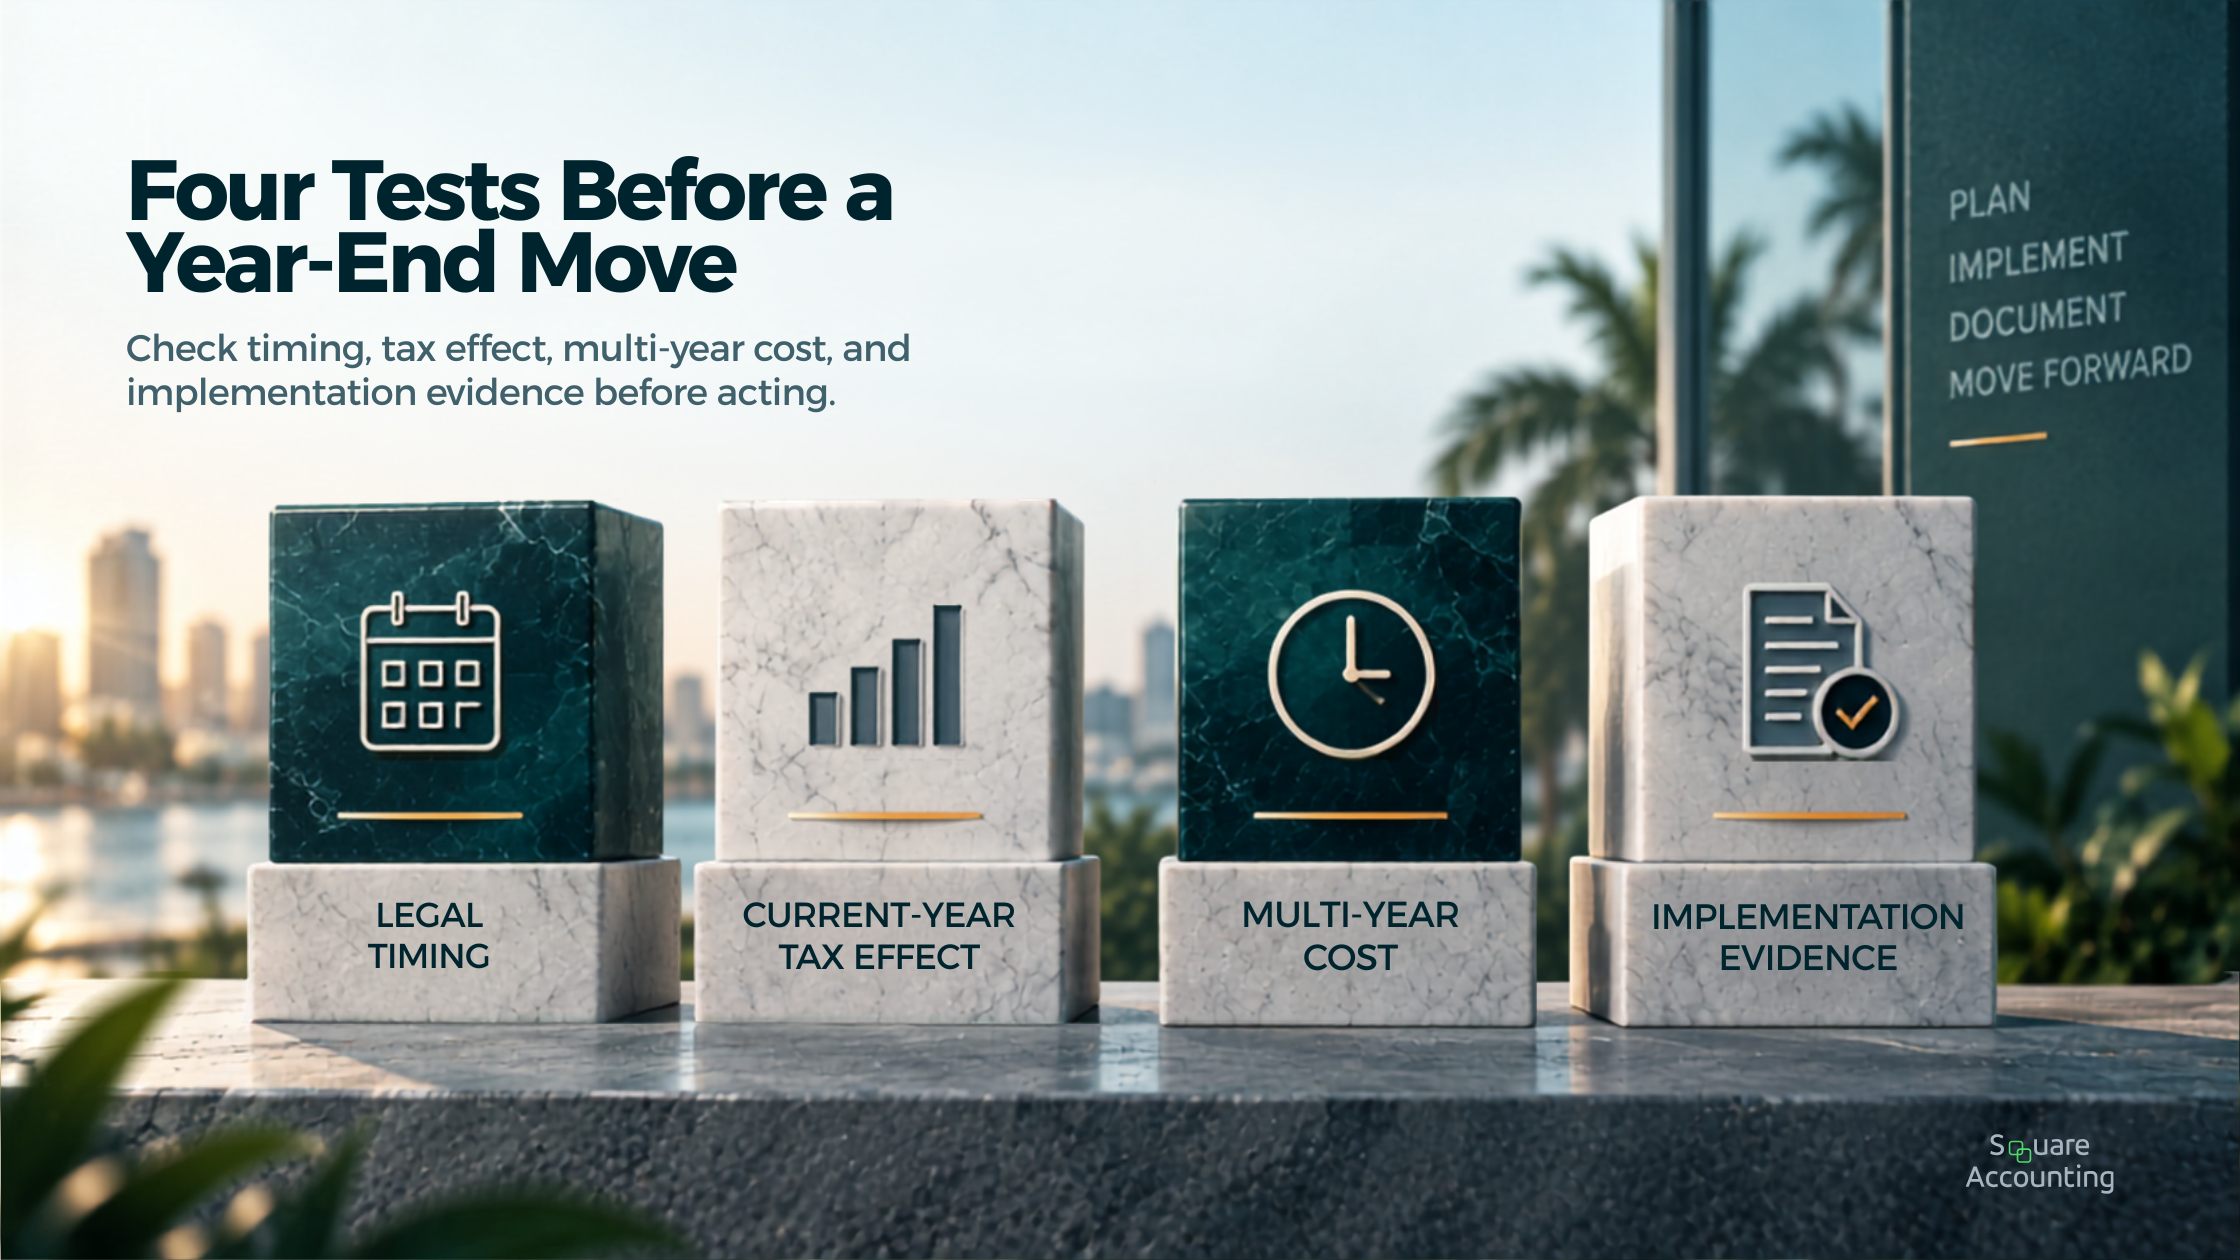
A year-end strategy should be evaluated as an implementation decision, not simply as an available tax provision.
“This framework is deliberately stricter than a list of tax tactics. It gives an owner a way to reject a technically available move when the economics, evidence, or exit consequences are weak.”
Coordinate legal timing, current-year tax effects, multi-year costs, and implementation requirements before acting.
Build the Evidence File While the Year Is Still Open
Year-end planning is easier to defend when the implementation record is created at the same time as the decision.
For a 2026 review, gather:
current profit-and-loss statement and balance sheet;
year-to-date payroll reports;
2025 federal return;
estimated-payment and withholding history;
expected K-1 information;
realized investment gains and losses;
retirement-plan documents and elections;
invoices, purchase records, and placed-in-service support for major assets;
charitable acknowledgments and noncash-gift records; and
a short list of material 2027 events, including acquisitions, financing, ownership changes, or a potential sale.
The point is not paperwork for its own sake. Each document should connect to a tax position, a payment decision, or a future-year assumption.
Where Year-End Plans Commonly Fail
The recurring failures are usually coordination failures rather than obscure tax rules.
Safe harbor is treated as the final tax bill. The penalty target is met, but filing-season liquidity is not reserved.
An S corporation salary is set by a percentage rule. The amount is not tied to the shareholder's services or the company's actual economics.
A retirement contribution is assigned the wrong deadline. Employee deferrals, employer contributions, and SEP funding are treated as though they follow the same clock.
An asset is purchased to create a deduction. Business need, cash pressure, later business use, and disposition consequences are not modeled.
Income is “deferred” after constructive receipt has already occurred. The bookkeeping entry does not change the tax timing.
A portfolio loss is harvested without checking replacement purchases. A wash sale changes the expected result.
Florida residency is treated as a complete state-tax answer. Entity, payroll, sales/use, or another state's rules may still require review.
The Year-End Goal Is a Better Tax Position, Not a Longer Checklist
A strong 2026 year-end tax planning checklist for business owners should leave you with three clear outputs: the decisions that must be completed while 2026 is still open, the items that can be completed later under the applicable rules, and the moves that should be declined because the tax benefit does not justify the liquidity, documentation, or future-year cost.
For a high-income Florida owner, that usually requires one coordinated model connecting the business, payroll, retirement decisions, investment activity, estimated taxes, and the individual return, with at least a directional 2027 case.
If those pieces are currently being reviewed separately, a Tax Prep + Advisory Review can be used to reconcile the 2026 projection, identify the actual decision deadlines, and show which actions improve the combined current- and next-year position before implementation.
Clarify which 2026 actions still require attention, which can wait, and how they fit with the projected 2027 position.
2026 and 2027 planning
Year-End Tax Planning FAQs
These questions connect income projections, payroll, deductions, liquidity, future transactions, and implementation evidence before the remaining decision windows close.
If projected 2026 income changes materially late in the year, what
parts of the tax plan should be reconsidered?
Reopen the parts of the plan that depend on taxable income rather than changing one item in isolation. The final article identifies estimated-tax funding, withholding, Section 199A, retirement contributions, charitable planning, and investment-income interactions as areas that can move when the income projection changes. The 2027 case should also be refreshed because a deduction that becomes more attractive in 2026 may become less attractive if next year's income or liquidity needs have changed. The objective is to update the coordinated model before implementing discretionary year-end moves.
Why can final payroll affect more than an S corporation owner's
reasonable compensation analysis?
Final payroll can connect several decisions that otherwise look separate. The article identifies reasonable compensation, federal withholding, retirement contributions tied to compensation, distributions, shareholder health-insurance treatment where applicable, and the consistency of payroll with the books as year-end review items. Because elective deferrals generally depend on compensation that has not already become currently available, payroll timing can also affect what remains implementable. The practical issue is therefore broader than selecting a salary figure. Compensation, withholding, retirement elections, and the business records should be reviewed together before payroll is closed.
When can the legal deadline be later than the last practical decision
point?
A later statutory or filing deadline does not necessarily mean every underlying decision can also wait. The final article distinguishes employer retirement contributions and SEP funding, which may remain possible after year-end, from employee elective deferrals that generally depend on compensation not already being available. Similar timing distinctions apply to payroll, charitable delivery, investment sales, and property placed in service. The practical decision point is when the required action, election, transaction, documentation, or operational step can still be completed correctly, not simply the last date on which a related payment may occur.
How should a possible 2027 sale or ownership change affect 2026
year-end planning?
It should become part of the 2026 projection before discretionary deductions or asset purchases are accelerated. The article specifically identifies ownership changes and potential sales as future events that can change the value of current-year decisions. For depreciable assets, the analysis can include liquidity, future basis, business-use changes, and possible depreciation recapture when property is later disposed of. A current deduction may still be useful, but the decision should be evaluated against the expected exit path rather than viewed only through the 2026 tax result.
Why should a business owner separate the tax benefit from the cash
decision?
Because a tax deduction, payment decision, and cash outflow answer different questions. The article separates projected tax liability from required prepayments and cash reserves, and it applies the same discipline to asset purchases and retirement funding. A technically available deduction can still create pressure on working capital or reduce flexibility for a higher-income future year. The planning judgment is therefore not simply whether an expenditure is deductible. It is whether the timing of the expenditure fits the owner's projected tax position, liquidity needs, and expected 2027 business requirements.
Why can two service-business owners with similar profits reach
different year-end conclusions?
Similar business profit does not mean the owners have the same individual tax picture. The final article requires the projection to consider wages, pass-through income, spouse income, investment gains, retirement contributions, charitable deductions, withholding, estimated payments, and expected changes in the following year. Business classification and owner compensation can also affect the analysis. Two owners can therefore start with similar operating income but face different planning priorities because their individual returns, cash needs, retirement arrangements, investment activity, and 2027 expectations are different.
What makes a year-end strategy ready to implement rather than merely
available?
The article's framework requires more than finding a tax rule that permits an action. The owner should know the controlling timing event, understand whether the effect is a deduction, deferral, credit, payment-timing change, or other tax consequence, evaluate the multi-year cost, and identify what implementation evidence is required. That can include payroll records, elections, plan documents, invoices, placed-in-service support, charitable acknowledgments, and other records tied to the transaction. A strategy is implementation-ready when the tax position, operational steps, and supporting evidence are aligned with the facts being reported.
Inzamam ur Rahman
Content & Marketing Strategist
Inzamam manages content and advises on marketing strategy for Square Accounting. He works with Stevan Franeta, CPA, to create clear, practical articles for business owners, high-income professionals, and real estate investors.
Reviewed for tax accuracy by Stevan Franeta, CPA
