
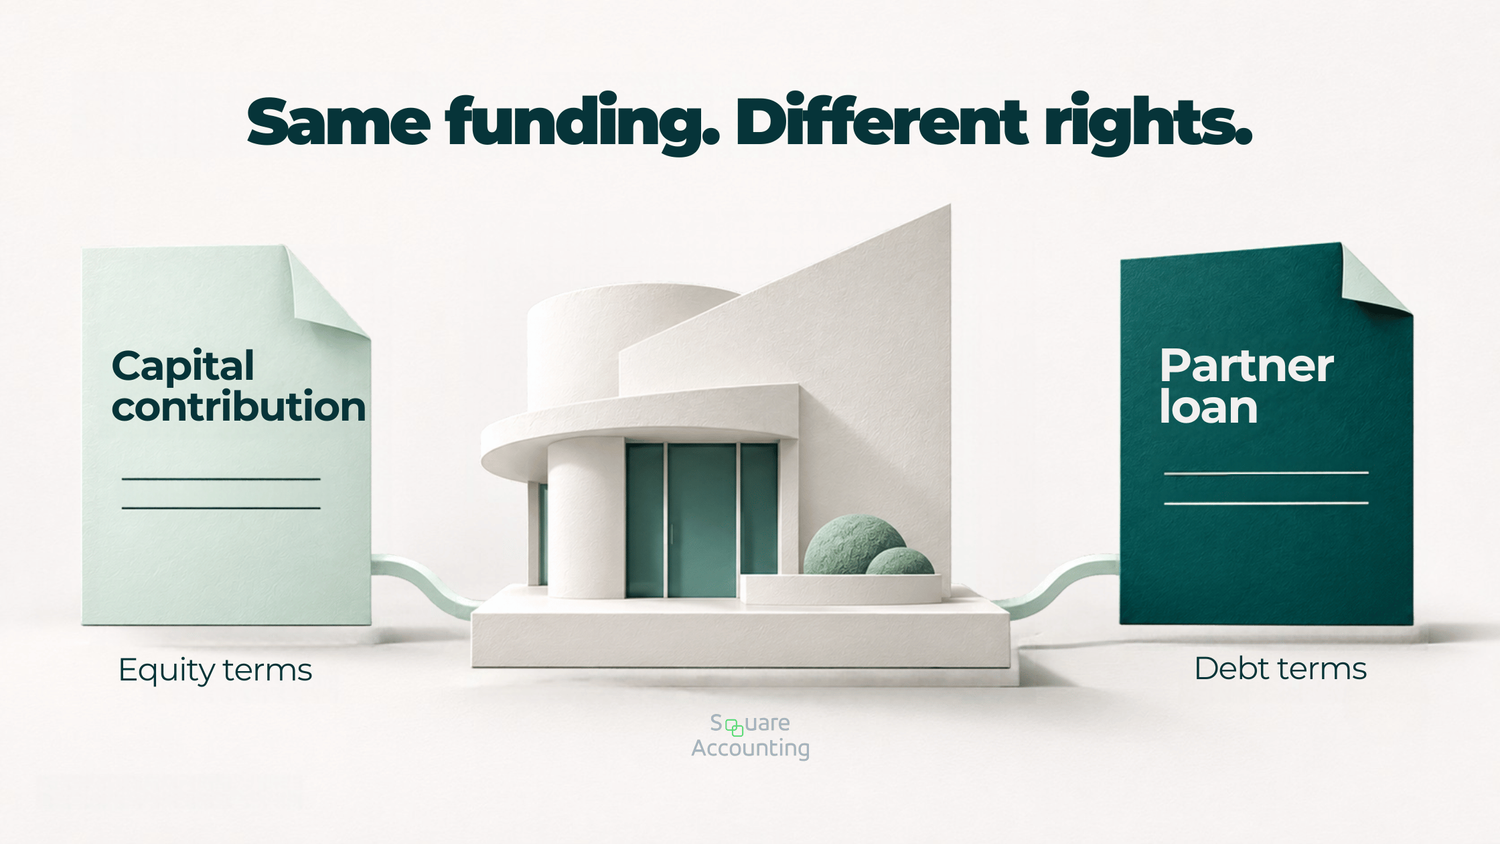
The funding terms determine the equity or creditor relationship; repayment and tax treatment require separate review.
A capital contribution funds the partnership as equity. A partner loan creates a separate creditor relationship if it is bona fide debt. The choice affects repayment rights, capital accounts, interest, and tax reporting. Both arrangements can affect a partner’s outside basis, but neither automatically makes partnership losses deductible.
If you are comparing capital contributions vs. loans to a partnership, start with what the partners intend to happen when the money comes back. Should the advance participate in the project’s economics, or should the partnership owe a defined debt? Then check whether the agreement, cash-flow forecast, and tax treatment support that answer.
This guide addresses partnerships and LLCs taxed as partnerships. S corporation shareholder-loan rules require a separate analysis.
What to resolve before funding
- Additional capital does not automatically change ownership percentages. Review the agreement’s capital-call, allocation, and distribution provisions.
- A genuine loan needs a credible repayment obligation and conduct consistent with lending.
- Outside basis, capital accounts, and the amount at risk measure different things.
- Loan repayment can reduce a partner’s share of liabilities, creating a separate basis consequence.
- Florida loan documents can carry documentary stamp tax even when the lender is already a partner.
Capital contributions vs. loans to a partnership: the key differences
The same cash deposit can support very different rights. Agree on those rights before choosing the bookkeeping account.
| Decision | Capital contribution | Bona fide partner loan |
|---|---|---|
| Legal position | Equity funding under the partnership agreement. | Separate creditor rights under the loan documents. |
| Ownership | Additional funding does not automatically change percentages. | The loan alone does not grant additional equity. |
| Cash return | Distributions depend on the agreement, available funds, and applicable law. | Principal and interest are owed under the note; collection remains uncertain. |
| Capital account | A cash contribution generally increases the contributing partner’s capital account. | Principal is recorded as debt, separate from contributed equity. |
| Outside basis | Cash generally increases outside basis, subject to other adjustments. | Allocated partnership liabilities can increase outside basis under Section 752. |
| Current deduction | Contributing money is not itself a deduction. | Lending principal is not itself a deduction. Partnership interest treatment needs separate review. |
A partnership can use both equity and partner debt. Keep each advance separately authorized and traceable. A later change in plans needs its own review; changing an account label does not rewrite the original transaction.
How a capital contribution works
A capital contribution adds money or property to the partnership’s equity funding. Section 721 generally provides nonrecognition for qualifying property contributions in exchange for a partnership interest. Cash is usually straightforward; appreciated property, associated debt, or related transfers can complicate the result. See Section 721.
Under Section 722, contributed cash generally increases the contributing partner’s outside basis by the amount contributed. Contributed property generally brings its adjusted tax basis rather than a fresh fair-market-value tax basis. Section 723 supplies the partnership’s general carryover-basis rule for contributed property.
The economic arrangement needs equal attention. An additional contribution might satisfy an existing capital call, earn a preferred distribution right, or change negotiated ownership. The operating agreement and any valid amendments determine those rights; a larger deposit alone does not supply the answer. Tax allocations must also satisfy Section 704.
Example: one partner contributes another $100,000
Illustrative assumptions: Maya and Leo each own 50% of an LLC taxed as a partnership. Maya contributes $100,000 of her own cash for renovations. Their agreement permits the contribution without changing their 50/50 profit shares and gives Maya a specified capital-return preference. Assume no associated borrowing, liability shifts, distributions, or other basis adjustments.
Maya’s outside basis generally increases by $100,000, and the contribution is reflected in her capital account. The partnership receives $100,000 of cash. Leo’s ownership does not automatically fall below 50%, and Maya does not automatically receive all future deductions. The agreed economics and valid allocation provisions still govern.
Before funding, both owners should understand whether the preference applies to operating cash, refinancing proceeds, sale proceeds, or all three. A capital-return preference is different from a scheduled debt repayment.
How a partner loan works
A partner may lend money while continuing to hold an equity interest. A bona fide loan is generally treated as a transaction outside the partner’s capacity as an owner under Section 707(a) and Treasury Regulation 1.707-1. The debt creates creditor rights; it does not, by itself, grant additional equity.
A useful loan file explains the principal, funding date, interest, maturity, payment schedule, default provisions, and any collateral or subordination. It should also explain how the partnership expects to repay. A fixed date provides little comfort if the business has no credible repayment source.
For federal tax purposes, a bona fide debt rests on a valid, enforceable obligation to pay a fixed or determinable amount. A capital contribution is not converted into debt by calling it a loan. Treasury Regulation 1.166-1(c) states this distinction in the bad-debt context.
Have counsel address enforceability, lender consent, collateral, and priority. An unsecured partner loan may sit behind secured financing, and a subordination agreement can restrict payments. Being a creditor does not guarantee recovery.
Example: the same $100,000 is a loan
Illustrative assumptions: Maya instead lends the LLC $100,000 under a bona fide note. The note bears an illustrative 6% simple annual interest rate, with principal outstanding for a full year. The rate is used only for arithmetic; it is not a recommended rate or an AFR safe harbor.
Annual stated interest is $100,000 × 6% = $6,000. The partnership records a $100,000 loan payable, separate from Maya’s capital account. Her equity percentage stays 50% under the unchanged agreement. Interest treatment and the partnership’s ability to deduct or capitalize it require the separate analysis below.
For outside basis, assume the liability qualifies under Section 752 and is allocated entirely to Maya under the partner-lender rules, with no offsetting liability shifts. Her outside basis then increases by $100,000. Do not add another $100,000 as a capital contribution: the same advance is not both contributed equity and debt.
Does a loan to a partnership increase basis?
It can. Under Section 752, an increase in a partner’s share of partnership liabilities is treated as a contribution of money. The result depends on the liability and its allocation, rather than simply whether the note is labeled recourse or nonrecourse.
For recourse liabilities, Treasury Regulation 1.752-2 generally looks to economic risk of loss. Its partner-lender rule can assign that risk to a partner making a loan, including certain loans described as nonrecourse in the documents, where another partner does not bear the risk. Exceptions and overlapping obligations can change the allocation.
For liabilities treated as nonrecourse under Section 752, Treasury Regulation 1.752-3 allocates liabilities through partnership minimum gain, specified built-in gain, and excess nonrecourse-liability rules. A personal guarantee is not a universal requirement for outside basis.
Making a direct loan and guaranteeing a bank loan are different transactions. A guarantee must be evaluated under the applicable payment-obligation rules; signing one does not automatically establish the desired tax result.
Keep these four records separate
| Record | What it tracks | Why it matters |
|---|---|---|
| Inside basis | The partnership’s tax basis in its assets. | A cash deposit does not automatically increase the basis of an existing building. |
| Outside basis | The partner’s tax basis in the partnership interest. | Includes qualifying liability allocations and other partner-level adjustments. |
| Tax-basis capital | The partner’s capital reported using the tax-basis method. | Generally excludes the partner’s share of partnership liabilities; it is not a substitute for outside basis. |
| Section 704(b) book capital | Capital maintained under the applicable economic-allocation rules. | May differ from tax-basis capital, particularly for contributed or revalued property. |
For Section 704(b) book capital, contributed property can be recorded using fair market value under the applicable rules, while tax basis can remain tied to adjusted tax basis. That difference matters when a partner contributes appreciated real estate. Treasury Regulation 1.704-1 addresses book capital and allocation requirements.
Why basis does not guarantee a deductible loss
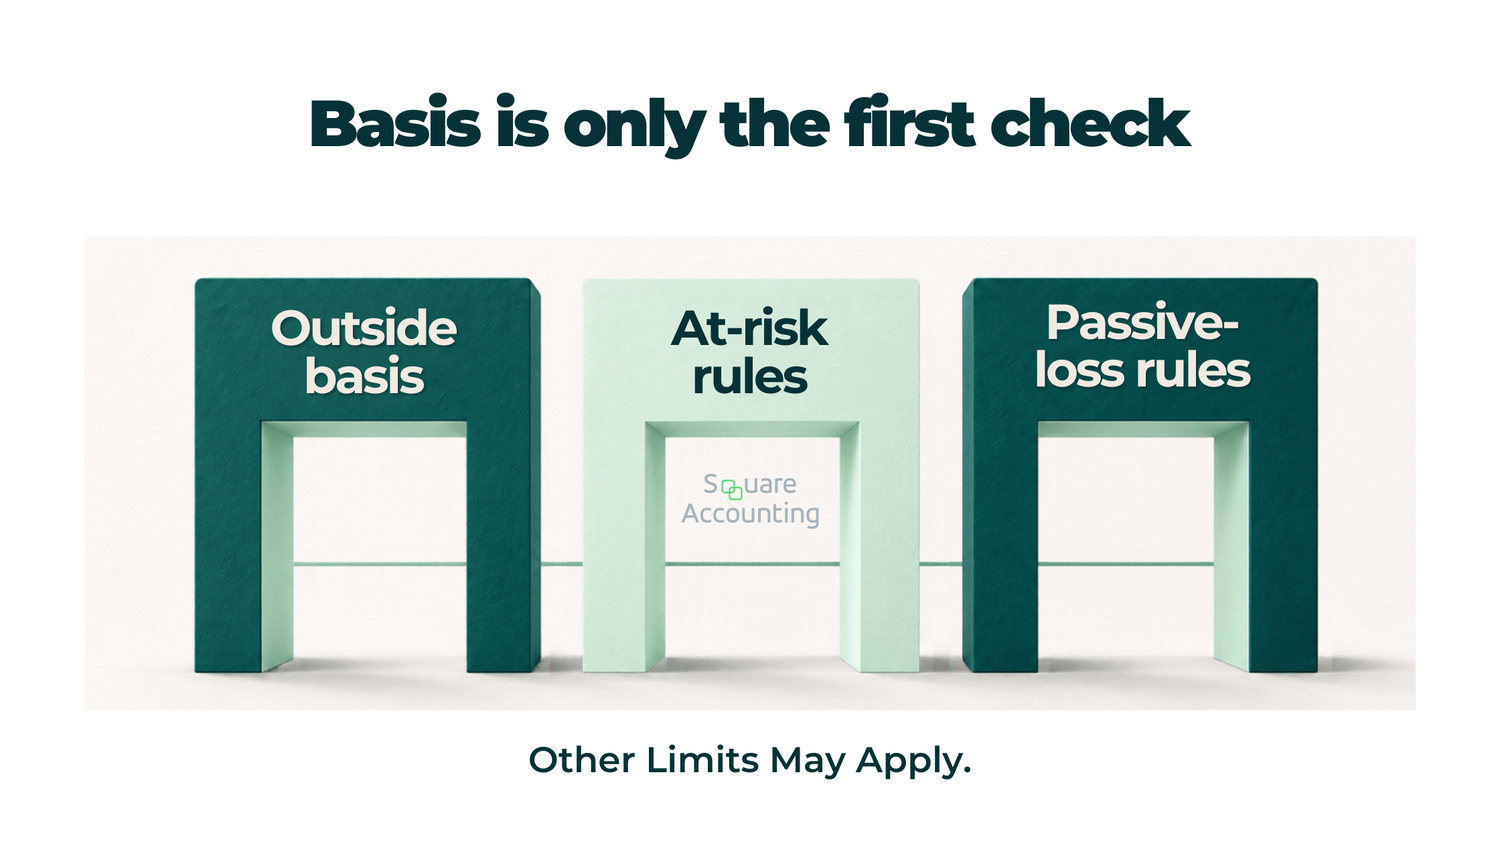
More outside basis does not automatically make a partnership loss deductible. At-risk, passive-loss, and other limits may apply.
Apply the relevant limitations separately. Section 704(d) limits partnership losses by outside basis. Section 465 separately limits covered losses to the amount at risk. Ordinary nonrecourse borrowing may create outside basis without creating an equal at-risk amount; qualifying nonrecourse financing has specific requirements.
Section 469 can then suspend passive losses. Rental activities are generally passive unless an exception applies. Other taxpayer-level limits may also apply. A funding decision should therefore include a forecast of when losses may actually be used, rather than assuming a current tax benefit.
Interest, principal repayment, and exit planning
Interest received by the lending partner is generally taxable interest income under Section 61. It is not a deduction to that partner merely because the partnership pays it.
The partnership analyzes its own interest expense. The use of loan proceeds, capitalization requirements, and applicable Section 163 limitations, including Section 163(j) where applicable, affect whether and when a deduction is available. A loan used for a development project should not be assumed to generate an immediate expense deduction.
Accounting-method matching also matters. An accrual-method partnership generally cannot deduct a business expense owed to a cash-method partner before payment; guaranteed payments have separate treatment. Review IRS Publication 541 and Section 267 before relying on accrued, unpaid interest.
Document why the interest terms fit the arrangement. Section 7872 addresses specified below-market loans, including certain tax-avoidance arrangements. Its application depends on the facts. Quoting an AFR does not settle debt-versus-equity classification, state-law requirements, or every pricing issue.
Principal repayment can have a second tax effect
For an ordinary cash-funded loan repaid at its outstanding tax basis, principal recovery generally does not create interest income or a partnership deduction. But repayment also reduces partnership debt. A reduction in the partner’s allocated liabilities is treated as a money distribution under Section 752(b).
That deemed distribution must be reconciled with the partner’s outside basis and other distributions. Under Section 731, a money distribution can trigger gain when it exceeds available outside basis. The principal check alone does not show the entire tax result.
Returning equity also needs a distribution analysis. Review the operating agreement’s waterfall alongside the basis schedule before a refinancing, partner buyout, or sale. A preferred equity return may be an allocation/distribution arrangement or involve guaranteed-payment rules; the word “preferred” does not make it loan interest.
Florida considerations: the note can create a state tax cost
Florida’s documentary stamp tax reaches certain written payment obligations, including taxable promissory notes signed or delivered in Florida. A loan from an existing partner is not automatically exempt.
The general note rate is $0.35 for each $100, or fraction thereof, of the obligation, with a $2,450 cap on the note tax. That cap does not apply to recorded mortgages or other recorded liens. Exemptions, renewals, and tax previously paid can affect the result. See the Florida Department of Revenue’s documentary stamp guidance.
Illustration: a taxable $100,000 unsecured note, assuming no exemption and no other relevant document, produces $350 of documentary stamp tax: 1,000 × $0.35.
If the obligation is secured by Florida real property, also evaluate nonrecurring intangible tax. Florida generally imposes it at 2 mills on the taxable secured obligation. On a fully taxable $100,000 obligation, that is $200. Security arrangements, exemptions, and allocation rules matter; this is separate from documentary stamp tax.
A contribution of real estate requires a separate deed, debt, and transfer-tax review. The cash-funding comparison above should not be used as a shortcut for transferring an already mortgaged property into an LLC.
Before you transfer money: a partnership funding checklist
- State the commercial purpose. Identify the amount, use of funds, and expected holding period.
- Agree on the economics. Decide ownership, profit sharing, repayment rights, and how sale or refinancing proceeds will be applied.
- Test the cash flow. Show whether scheduled debt service is realistic and what happens if the project underperforms.
- Approve the documents. Have counsel coordinate the agreement, note, security, existing lender restrictions, and required consents.
- Model the tax consequences. Reconcile capital, outside basis, liability allocations, at-risk amounts, interest treatment, and suspended losses.
- Check Florida document taxes. Assign responsibility for calculating and paying any tax due.
- Maintain the records. Keep bank evidence, payment histories, approvals, capital schedules, and partner-level basis records aligned.
Do not postpone an unclear classification until the return is being prepared. If funds have already moved, reconstruct the contemporaneous facts and obtain advice on the proper treatment. Do not backdate documents or assume a year-end journal entry resolves missing economic terms.
What if the partnership cannot repay a partner loan?
A failed project does not automatically produce an ordinary deduction for the lender. Section 166 distinguishes business and nonbusiness bad debts. For a noncorporate lender, a wholly worthless nonbusiness debt generally receives short-term capital-loss treatment. Debt cancellation can also affect the partnership and its owners, so review a workout before forgiving or converting the balance.
Choose the economics first, then align the tax reporting
Capital generally fits money intended to remain exposed to the partnership’s equity economics. A loan generally fits a genuine lending arrangement with defined obligations and a credible repayment source. Some partnerships need both.
The useful comparison is how each alternative affects the funding partner, the other owners, and the partnership over the holding period and exit. Match the agreement, accounting, and tax schedules to that decision before relying on a projected deduction or repayment preference.
Frequently asked questions
Can I split an advance between capital and a loan?
Yes, if the arrangement genuinely contains both. Document the equity portion and debt portion separately, obtain the required approvals, and trace each amount in the books. The debt portion still needs a credible repayment obligation.
Does contributing more money automatically increase my ownership?
No. Review the agreement’s capital-call, dilution, allocation, and distribution provisions. An additional contribution can change capital balances without changing negotiated ownership or profit shares.
Can nonrecourse partnership debt increase outside basis?
Yes. Section 752 and its regulations can allocate nonrecourse liabilities to partners. Outside basis does not establish an equal amount at risk or guarantee a usable loss. Direct partner loans also require the special partner-lender analysis.
Is the lending partner’s note receivable the same as outside basis?
No. The loan receivable and the partnership interest are separate assets. A qualifying liability allocation can affect outside basis while the lender separately tracks the note. Do not also record that same loan advance as a capital contribution.
Can I deduct money I lend to my partnership?
Lending principal is not itself deductible. Partnership losses have their own allocation and limitation rules. A later worthless debt requires a separate Section 166 analysis; it is not automatically an ordinary loss.
Is a preferred return the same as loan interest?
No. A preferred return can belong to the equity distribution arrangement or involve guaranteed-payment treatment, depending on its terms. A stated percentage alone does not establish debt or determine tax character.
Can I change an existing capital contribution into a loan?
Do not assume that a bookkeeping reclassification changes the original transaction. Review the original facts and the tax and legal consequences of any new arrangement before amending documents or moving money.
What should I bring to a partnership funding discussion?
Bring the operating agreement and amendments, proposed funding terms, recent financial statements, prior partnership returns and K-1s, partner-level basis and suspended-loss schedules, existing debt documents, and a cash-flow forecast through repayment or exit.
Inzamam ur Rahman
Content & Marketing Strategist
Inzamam manages content and advises on marketing strategy for Square Accounting. He works with Stevan Franeta, CPA, to create clear, practical articles for business owners, high-income professionals, and real estate investors.
Reviewed for tax accuracy by Stevan Franeta, CPA
